7.50% Is the Headline The Deal Is the Story Mortgage rates around 7.50% are understandably getting the attention. But the published rate is only part of the affordability story. The other part is the deal. Buyers today have negotiating tools that were largely absent during the COVID-era market: seller concessions, closing-cost assistance and rate buydowns.
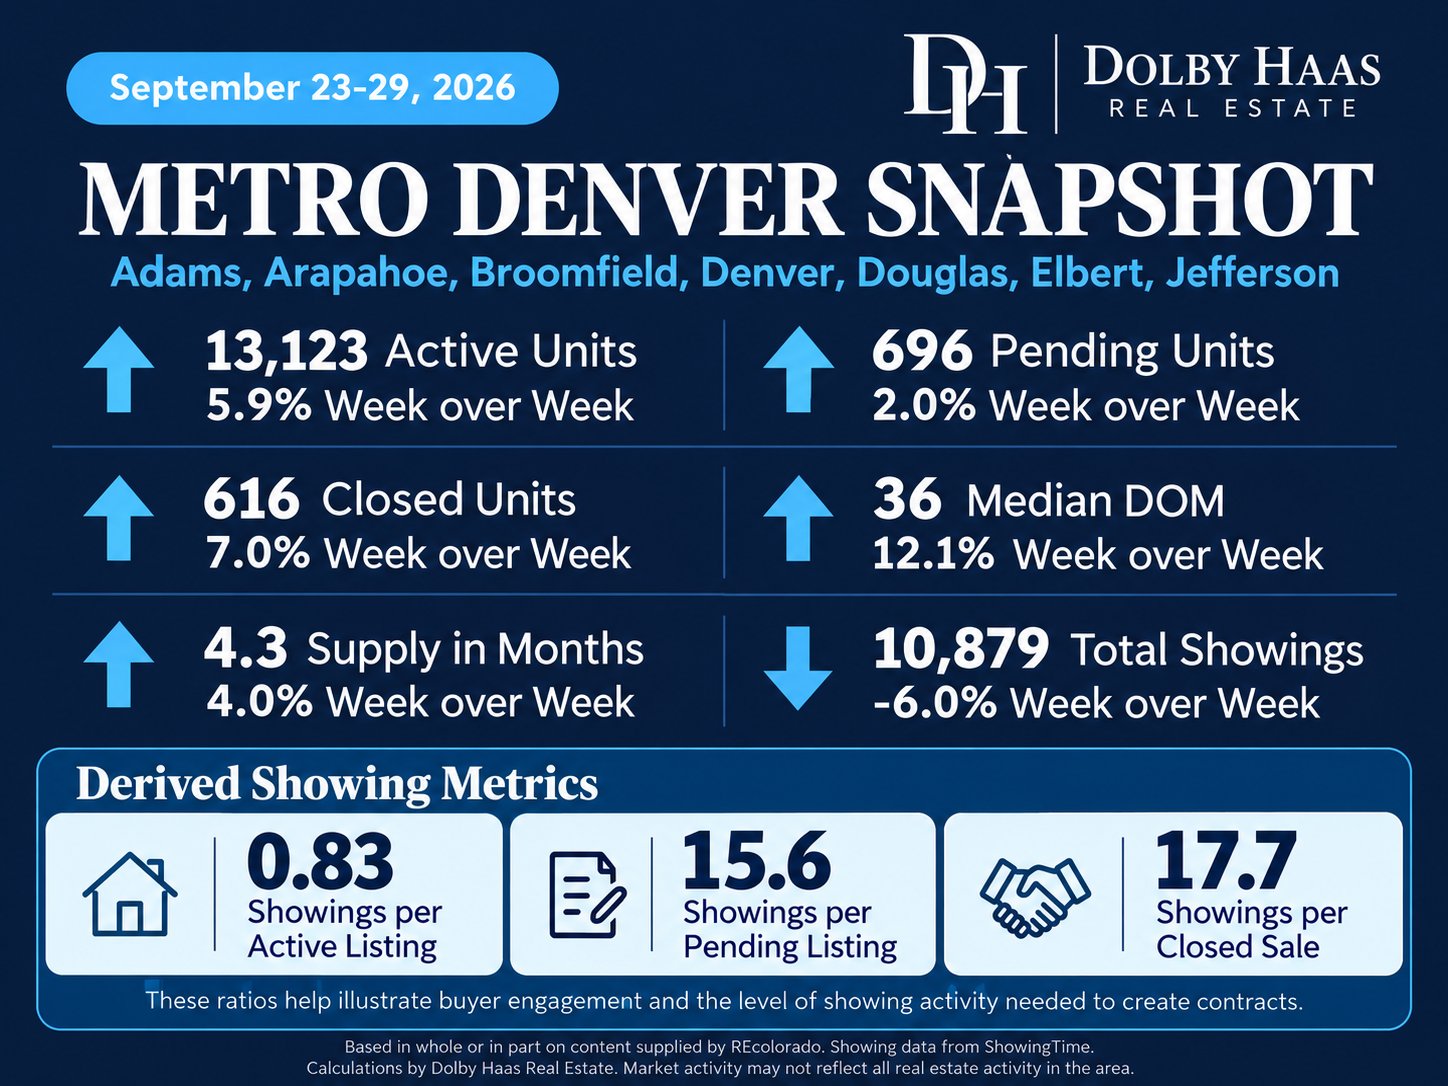
The Showing Data MattersFor September 23-29, Metro Denver recorded 13,123 active listings, 696 pending sales and 10,879 total showings.
0.83 Showings per active listing | 15.6 Showings per pending sale | 17.7 Showings per closed sale |
Two points stand out: total showings are now lower than they were in early January, and showings per active listing are at their lowest level of the year.
Some of that is seasonal. But 7.50% mortgage rates are clearly part of the story too. Buyers have more choices, they are more payment-sensitive, and each showing matters more.
What Concessions Can DoSo far in 2026, roughly four out of five financed transactions have included some form of concession, with an average concession around $12,000.
Metro Denver ExampleOn an approximately $805,000 home with 10% down, principal and interest at 7.50% is roughly $5,050 per month. If a buyer negotiates a $12,000 seller concession, those funds could be applied toward an approved permanent or temporary rate buydown, depending on lender pricing and the buyer's loan program.
For illustration, a buydown that reduces principal and interest by about $200 per month would bring the payment to roughly $4,850. The exact rate achieved cannot be assumed from the concession amount alone because mortgage pricing changes daily and varies by borrower, loan type, LTV and lender.
The benefit can show up as a lower monthly payment or potentially greater purchasing power while keeping the buyer's monthly budget near the same level.
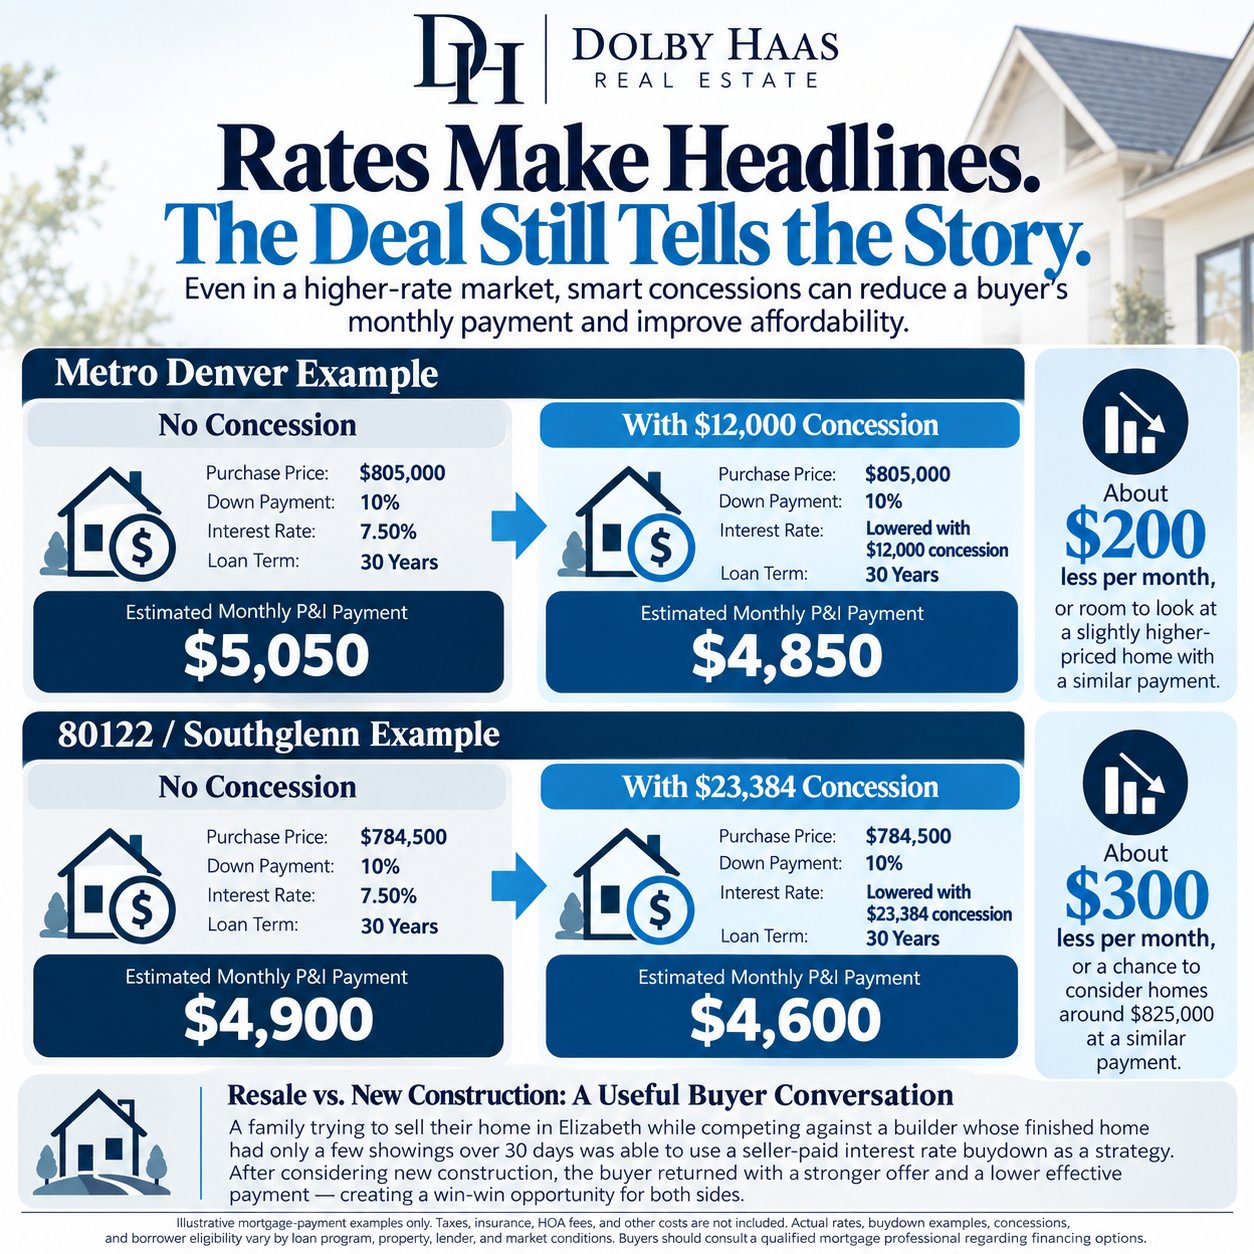
Southglenn / 80122 ExampleIn 80122, concessions on single-family homes averaged about $23,384 in August. Because this is a much larger concession than the Metro Denver example, it may support a more substantial buydown.
On a roughly $784,500 home with 10% down, principal and interest at 7.50% is about $4,900 per month. If lender pricing allowed that larger concession to reduce the rate to around 6.75%, the payment could fall to roughly $4,600 per month.
That is roughly $300 per month. The key point is that these examples are not showing the same buydown at different prices. They illustrate how different concession amounts can create different financing outcomes. Actual rate reductions and costs depend on lender pricing and borrower qualifications.
For Sellers, Payment Can Matter More Than Another Price CutResale sellers are also competing with new-home builders that may be offering major incentives and subsidized mortgage rates. That means the competition is no longer just about purchase price. It is about the buyer's monthly payment.
A strategic concession may sometimes do more to improve affordability than another modest price reduction. The right answer depends on the property, price range, financing and local competition, but sellers should run the numbers before automatically cutting price.
Negotiate the Transaction, Not Just the PriceBuyers are still buying. They are simply more selective, more payment-sensitive and more willing to negotiate.
For sellers, the goal is not just to get a buyer through the door. It is to create a transaction that makes enough financial sense for that buyer to act.
Price matters. Payment matters. Concessions matter.
The rate makes the headline. The deal tells the story.
Mortgage-payment examples are illustrative only and are not loan quotes. Actual mortgage rates, payments, seller concessions, buydown costs and borrower eligibility vary by loan program, lender, property, borrower qualifications and market conditions. Seller concession amounts do not correspond to a fixed or guaranteed rate reduction. Principal-and-interest examples do not include taxes, insurance, HOA fees or other housing expenses. Buyers should consult a qualified mortgage professional before making financing decisions. 
|